How to Assess Flood Risk Before Buying a Home

A beautiful home can sit on a street that has never visibly flooded and still carry meaningful water-related risk. A sudden summer storm, overwhelmed municipal system, blocked catch basin, nearby creek, or low lot elevation can change the picture quickly. Knowing how to assess flood risk before you buy, sell, or invest is not about avoiding every property with a water feature nearby. It is about understanding the specific exposure, likely costs, available protections, and resale implications before making a major financial decision.
For buyers across Halton, Hamilton, Niagara, and the GTA, this research deserves the same attention as financing, a home inspection, and comparable sales. For sellers, preparing clear information early can reduce surprises during conditional periods and support a more confident transaction.
Start With the Type of Flood Risk
“Flood risk” is a broad term. A property near a river may face riverine flooding when watercourses overflow, while a home far from any creek may be vulnerable to overland flooding after heavy rainfall. Overland flooding occurs when rainwater or melting snow flows across the ground and enters a property. Sewer backup is different again: municipal pipes can become overloaded, potentially forcing water back through drains or lower-level fixtures.
Lakefront and shoreline properties can also face wave action, erosion, changing water levels, and drainage challenges. In areas near Lake Ontario, the Niagara River, or Hamilton Harbour, these considerations can affect insurance, maintenance planning, and future improvements.
The source matters because the solution changes. A backwater valve may help reduce sewer-backup exposure, but it will not stop water entering through a low patio door during an intense overland event. Similarly, a home outside a mapped floodplain can still have a history of basement seepage or surface-water ponding.
How to Assess Flood Risk Using Official Mapping
Your first step should be reviewing available floodplain and hazard mapping. In Ontario, municipalities and local conservation authorities often publish mapping that identifies regulated areas, floodplains, watercourses, wetlands, and hazard lands. These tools are useful screening resources, but they are not a complete guarantee of safety or risk.
A property inside or adjacent to a regulated area may require approval before certain projects can proceed, such as additions, grading changes, pools, retaining walls, or rebuilding after major damage. That does not automatically make it a poor purchase. It does mean the buyer should investigate planned improvements carefully before removing conditions.
Look beyond the lot itself. Review the surrounding topography, nearby creeks, stormwater ponds, culverts, ravines, and low-lying roadways. Water follows the landscape, and the lowest point in a neighborhood may be several houses away from the nearest visible waterway.
Read Maps With the Right Questions
When reviewing a mapped hazard area, ask whether the property is within it, beside it, uphill from it, or connected to it through drainage patterns. Find out whether the map identifies a regulatory floodplain, a fill-regulated area, a wetland, or another environmental feature. Each designation has different implications.
Mapping can also be dated. Flood models improve over time, development changes runoff patterns, and severe rainfall events can reveal issues that older mapping did not fully capture. Use maps as the start of due diligence, not the final answer.
Inspect the Property for Practical Warning Signs
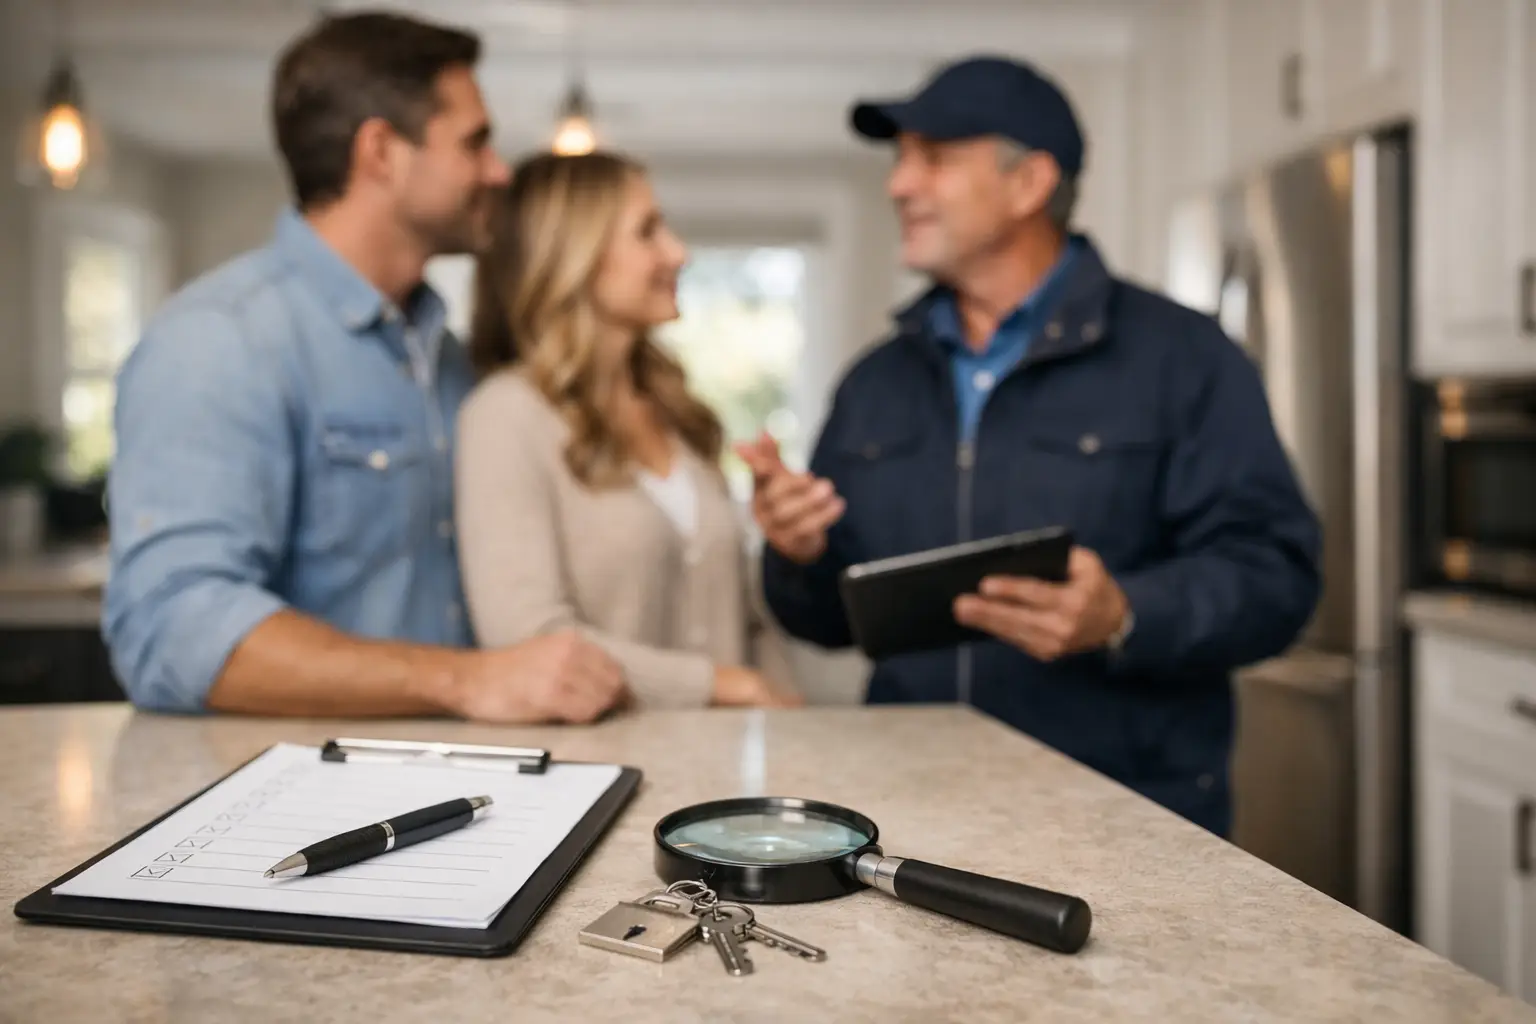
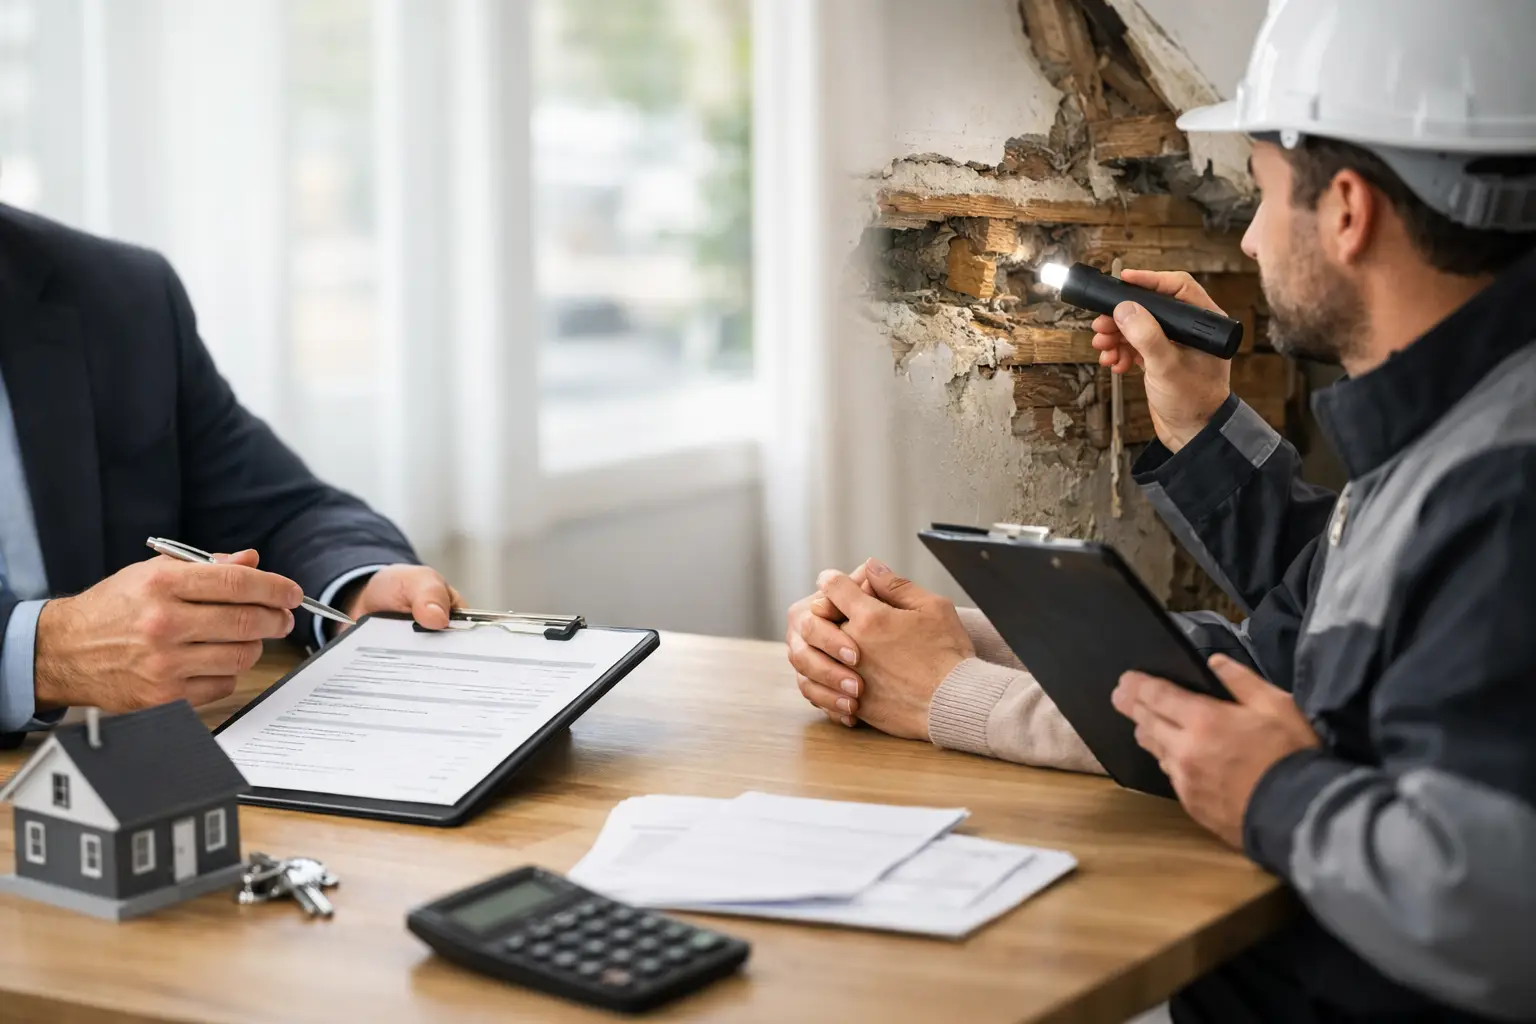
A qualified home inspector can identify visible moisture concerns and drainage deficiencies, but buyers should also pay close attention during their own visits. The goal is not to diagnose a problem on the spot. It is to recognize when further investigation is warranted.
Look for grading that slopes toward the house, downspouts that discharge beside the foundation, standing water near the exterior, damaged window wells, deteriorated caulking, or cracks around foundation walls. Inside, watch for fresh paint in a basement corner, a dehumidifier running continuously, musty odors, warped baseboards, water staining, efflorescence on concrete, or patched drywall near floor level.
None of these items proves a flooding issue. A well-maintained older home may have minor efflorescence without an active concern, while a recently renovated basement may conceal prior repairs. Context matters. Ask for invoices, permits, warranties, and details of any waterproofing, drainage work, sump-pump installation, or foundation repair.
Do Not Skip the Sewer Questions
For homes with finished basements, ask whether a backwater valve, sump pump, battery backup, or alarm is installed and functioning. Request information on the age and servicing of these systems. If there are signs of recurring drainage trouble, a sewer scope inspection can be a sensible added cost during a conditional period.
Older neighborhoods can have infrastructure that differs from newer subdivisions, but newer construction is not automatically risk-free. Rapid development, changing drainage patterns, and extreme rainfall can affect communities of any age.
Confirm Insurance Before You Firm Up
Insurance is one of the clearest real-world tests of a property’s flood exposure. Contact an insurance professional early, ideally while your offer is still conditional. Ask specifically about coverage for overland water, sewer backup, foundation water damage, and any exclusions, deductibles, coverage limits, or underwriting requirements.
Standard policies do not all offer the same protection. Availability and pricing can depend on the location, claim history, construction details, elevation, drainage, and insurer’s current guidelines. A property may be insurable but require higher deductibles or optional coverage. In some cases, a buyer may need to use a different insurer or accept limited water coverage.
This is also relevant for investors and landlords. Water-related repairs can interrupt a tenancy, create insurance claims, and affect carrying costs. Building wealth through real estate requires looking beyond the purchase price to the risks that could affect cash flow and future marketability.
Ask Direct Questions, but Verify the Answers
In Ontario, buyers should not assume that every past water issue will be obvious from a listing or a casual conversation. Ask the seller and listing representative whether the property has experienced water infiltration, sewer backup, overland flooding, insurance claims, foundation repairs, or drainage work. Ask whether the municipality has completed any nearby stormwater upgrades or basement-flooding protection programs.
Then verify what you can through documents, inspections, insurance discussions, and municipal or conservation authority inquiries. A seller may honestly say they have never experienced flooding, yet a prior owner may have. Conversely, a past issue that was professionally repaired may have been resolved and may not materially affect the property today.
The strategic question is not simply, “Has there ever been water?” It is, “What happened, why did it happen, what was done, and what does that mean for my ownership plans?”
Local Market Insight: Risk Can Affect Value, but Context Matters
In Halton, Hamilton, Niagara, and the GTA, proximity to water, ravines, and conservation lands can be a major lifestyle advantage. These locations may offer mature trees, privacy, views, trail access, and a sense of space that is hard to replicate. They may also require more careful due diligence around drainage, permits, maintenance, and insurance.
Market impact depends on the property and buyer pool. A well-protected home near a regulated area with documented improvements and reliable insurance may remain highly desirable. A property with unresolved water intrusion, limited insurance options, or restrictions that interfere with planned renovations may attract more cautious buyers and require more thoughtful pricing.
For sellers, transparency and preparation can be valuable. Documentation of waterproofing, sump-pump maintenance, grading work, and insurance history can help buyers evaluate the home based on facts rather than assumptions.
Build Flood Risk Into Your Offer Strategy
If early research raises concerns, use the conditional period wisely. Depending on the situation, this may include a detailed home inspection, sewer scope, insurance review, consultation with the relevant conservation authority, or review of permits and contractor invoices. Your approach should match the property’s actual risk profile, not a one-size-fits-all checklist.
A lower purchase price can sometimes offset manageable future costs, such as improving grading or replacing aging eavestroughs. It cannot always offset a serious limitation on insurability, rebuilding, or intended use. Buyers planning a basement renovation, accessory dwelling unit, extensive landscaping, or long-term rental should be especially thorough.
Frequently Asked Questions
Is a home near a creek always at high flood risk?
No. Distance from the creek is only one factor. Elevation, floodplain mapping, drainage design, lot grading, and local infrastructure all matter. A home farther away can still be exposed to overland water during intense rainfall.
Can a home outside a floodplain still flood?
Yes. Floodplain maps generally focus on defined water-related hazards. They may not capture every sewer backup, blocked drain, grading issue, or severe rainfall event that could affect a property.
Should flood history stop me from buying a home?
Not necessarily. The cause, repair quality, insurance availability, and your future plans all matter. A documented, resolved issue can be very different from recurring water damage with no clear solution.
What should sellers disclose about flooding?
Sellers should provide accurate answers to direct questions and should seek appropriate legal advice if they are uncertain about their obligations. Buyers should still complete independent due diligence rather than relying on disclosure alone.
A Consultative Next Step
If you are considering buying, selling, investing, or leasing in Halton, Hamilton, Niagara, or the GTA, the Ana Bastas Real Estate Team can help you evaluate property-specific risks alongside price, resale potential, and your broader goals. Experience the AB Advantage™ through strategic real estate advice grounded in local context and careful preparation.
Ana Bastas, ABR, SRS, SRES, RENE Team Leader | Wealth Builder Ana Bastas Real Estate Team (289) 670-5888
#FloodRisk #OntarioRealEstate #HomeBuyingTips #PropertyDueDiligence #HaltonRealEstate #HamiltonRealEstate #NiagaraRealEstate #GTARrealEstate
The best property decisions are made when the questions are asked early enough to give you real options.
Categories
- All Blogs (1214)
- Ana Bastas Real Estate Team (1)
- Ana Bastas Realtor (1)
- Ana bastas Realty (1)
- Brampton (1)
- Burlington (1)
- Buy & Travel™ Program (12)
- Buyer (209)
- Divorce (16)
- Downsizing (3)
- Events (8)
- First Time Home Buyers (138)
- Georgetown (1)
- Georgetown Buyers (8)
- Halton Hills (264)
- Hamilton (23)
- Holidays (1)
- How To (124)
- Interest Rates (1)
- Investor (4)
- Landlord (90)
- Lifestyle (128)
- Milton (51)
- Mississauga (1)
- Niagara (34)
- Oakville (2)
- Real Estate News (161)
- Realtor (20)
- Renter (94)
- Seller (185)
- Tax's (19)
- Tips (10)
- Toronto (135)
- Wealth Building (4)
- Wellington (2)
- YYZ (107)
Recent Posts

"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "