Ontario Buyer Deposit Rules and Smart Strategies

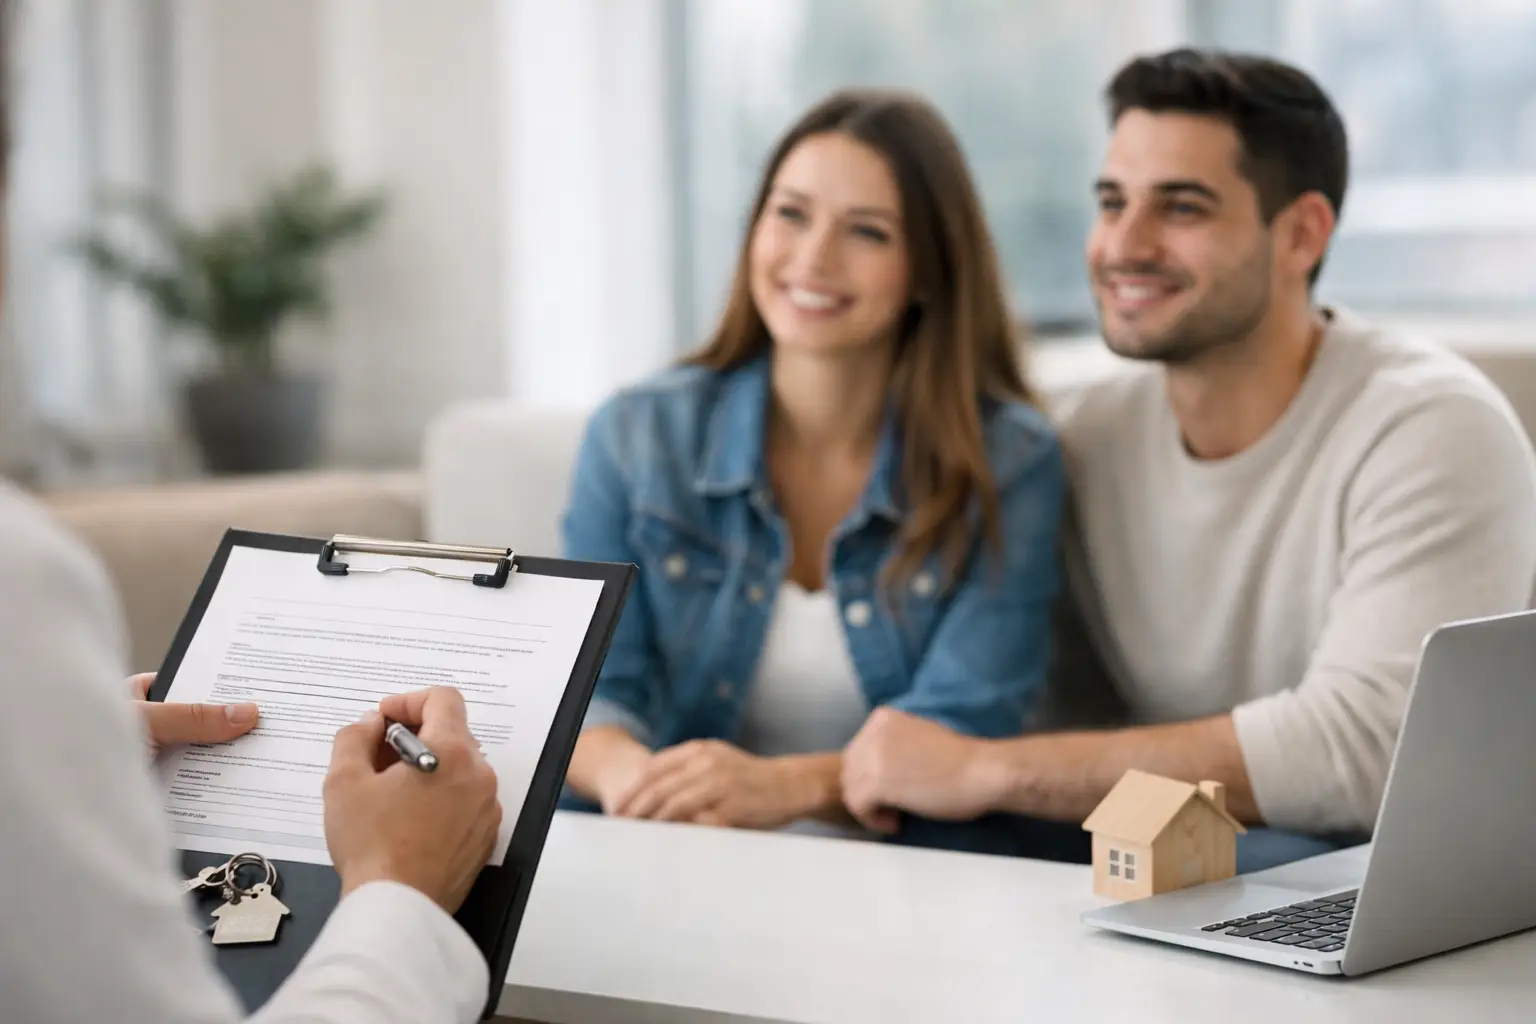
An Ontario buyer deposit is often the first substantial payment a buyer makes after an offer is accepted. It signals commitment to the transaction, but it is not simply money handed to the seller. The amount, timing, holder, and release terms can affect your negotiating position and your financial protection if the transaction does not close.
For buyers in Halton, Hamilton, Niagara, and the GTA, deposit decisions deserve more thought than a standard percentage. A well-structured deposit can strengthen an offer without exposing you to unnecessary risk. The right approach depends on the property, competition, financing, conditions, and your broader plan for buying and selling.
What Is an Ontario Buyer Deposit?
A deposit is money provided by the buyer after acceptance of an Agreement of Purchase and Sale. It forms part of the purchase price and is generally credited to the buyer on closing. It is different from the down payment, which is the portion of the purchase price the buyer contributes at closing after mortgage financing is considered.
For example, a buyer purchasing a $1,000,000 home may provide a $50,000 deposit shortly after acceptance. If they are financing 80 percent of the purchase price, their total down payment would be $200,000. The deposit is applied toward that $200,000 requirement, rather than added on top of it.
In many Ontario resale transactions, the deposit is held in trust by the listing brokerage until closing. In some cases, it may be held by a lawyer, depending on the agreement and how the transaction is structured. The Agreement of Purchase and Sale should clearly identify who receives the deposit, how much is due, and when it must be delivered.
How Much Should a Buyer Deposit Be in Ontario?
There is no legislated minimum deposit for an Ontario home purchase. In practice, the deposit is negotiated between buyer and seller. It is often expressed as a percentage of the purchase price, but a seller is evaluating more than the number alone.
A larger deposit can make an offer appear more credible, particularly when several buyers are competing for the same property. It shows the buyer has accessible funds and is prepared to move forward. In a quieter segment, however, an oversized deposit may not add much value if the offer already has strong financing, a reasonable closing date, and appropriate conditions.
A common range may be roughly 2 percent to 5 percent of the purchase price, although circumstances vary. In a competitive Oakville or Burlington family-home search, a seller may view a 5 percent deposit more favorably than a nominal amount. For a condo, an estate sale, or a property requiring extensive due diligence, the appropriate strategy may look different.
The central question is not, “What is the biggest deposit I can offer?” It is, “What amount demonstrates commitment while preserving my cash position and protecting my purchase?” Buyers should also leave room for closing costs, moving expenses, inspections, legal fees, and potential repairs after possession.
Timing Matters as Much as Amount
Ontario agreements commonly require the deposit within 24 hours of acceptance, although the parties can negotiate a different deadline. Missing that deadline can place the buyer in default under the agreement. If you plan to use money from an investment account, a sale proceeds account, or a family gift, confirm how quickly those funds can be accessed before submitting an offer.
The deposit should be delivered according to the written instructions in the agreement. Buyers should be cautious about wire fraud and payment scams. Verify deposit instructions directly with the brokerage or lawyer using a trusted phone number, especially if you receive new instructions by email at the last minute. Do not rely solely on an unexpected message or altered payment request.
When Is a Deposit Refundable?
Whether a deposit is refundable depends largely on the terms of the Agreement of Purchase and Sale and what happens after acceptance. A deposit is not automatically non-refundable just because an offer was accepted, but it is also not automatically returned whenever a buyer changes their mind.
Conditions are often the most practical protection. A financing condition may allow the buyer to confirm mortgage approval. An inspection condition can give the buyer an opportunity to assess the property’s physical condition. A condominium status certificate condition helps a condo buyer review financial, legal, and operational information about the corporation.
If a properly drafted condition is not satisfied or waived within the stated deadline, the agreement may become null and void, typically allowing the deposit to be returned. The exact wording matters. Buyers should understand who has the right to waive the condition, what notice must be delivered, and whether the condition is truly for their benefit.
If a buyer fails to close on a firm deal without a valid contractual basis, the seller may seek to retain the deposit and may also pursue further damages. The outcome depends on the agreement, the facts, and applicable law. A deposit dispute is not something to treat casually. Buyers facing a potential default should obtain legal advice promptly.
Firm Offers: Stronger, but Not Always Smarter
A firm offer has no conditions that allow the buyer to walk away during a due diligence period. In a multiple-offer situation, a firm offer with a meaningful deposit can be attractive to a seller because it reduces uncertainty.
That does not mean a firm offer is right for every buyer. Removing a financing condition before your lender has reviewed the specific property can create significant risk. This is especially relevant for properties with unique features, rural elements, rental suites, unusual zoning, major renovations, or appraisal concerns. A lender’s pre-approval is valuable, but it is not always a final commitment for every property.
For move-up homeowners, a firm purchase can also complicate the sale of the current home. You may have enough equity on paper, but the timing of sale proceeds, bridge financing, and your carrying costs all need to be considered. A strategic offer balances the desire to compete with the need to protect your household’s financial position.
Local Market Insight: Deposit Strategy Is Not One-Size-Fits-All
Across Halton, Hamilton, and Niagara, buyer behavior can vary by price point, property type, and neighborhood. A renovated detached home near sought-after schools in Milton or Burlington may attract buyers who are prepared with larger deposits and fewer conditions. A property in St. Catharines, Grimsby, or Hamilton that needs updates may warrant more time for inspections, financing review, and contractor input.
Condominium purchases need their own level of attention. In addition to the unit itself, buyers should consider monthly fees, reserve fund information, pending legal matters, rental rules, and upcoming building work. A status certificate review condition is often a sensible safeguard, even if the buyer is eager to make a competitive offer.
Investors should also avoid allowing deposit size to overshadow the property’s fundamentals. A stronger deposit may help win a deal, but it does not improve rental demand, carrying costs, insurance availability, or the return on planned renovations. Building Wealth Through Real Estate starts with disciplined underwriting, not simply winning the offer night.
Practical Steps Before You Write the Deposit
Before you submit an offer, confirm that your deposit funds are readily available and that your lender understands the intended purchase. Review the deposit clause carefully, including the amount, deadline, and trust holder. If conditions are included, make sure the deadlines are realistic and the wording aligns with the due diligence you actually need.
It is also wise to discuss the deposit alongside the full offer package. Price, deposit, closing date, inclusions, exclusions, conditions, and irrevocable time work together. A seller may prefer a slightly lower offer with cleaner terms and a reliable closing plan. Conversely, a high deposit does not necessarily overcome an aggressive price, an inconvenient possession date, or unclear conditions.
A thoughtful strategy is especially helpful when you are coordinating a sale and purchase, transitioning into retirement, or buying an investment property. Local Expertise. Proven Results. means looking at the transaction as a complete financial and lifestyle decision, not a single line on an offer form.
Frequently Asked Questions
Does the seller receive the deposit immediately?
Usually, no. The deposit is commonly held in a real estate brokerage trust account until closing or until the parties provide appropriate direction for its release. The seller does not generally receive it simply because the offer has been accepted.
Can I use a deposit from the sale of my current home?
Potentially, but timing is critical. If those sale proceeds are not available before your deposit deadline, you may need another source of funds or a negotiated deposit deadline. Never assume funds will arrive in time without confirming the closing schedule and banking process.
Is a bigger deposit always better?
Not necessarily. A larger deposit can improve the credibility of an offer, but it also places more of your money at risk if you do not meet your contractual obligations. The best deposit amount fits the property, market conditions, and your financial plan.
What if the listing brokerage asks for certified funds?
Follow the written instructions in the agreement and verify them directly with the brokerage. Certified funds or a bank draft may be requested to ensure the deposit is secure and promptly available. Be alert to changes in instructions and verify all payment details independently.
Speak With a Local Advisor Before You Offer
A deposit is a meaningful commitment, not just a standard formality. Before writing an offer, it helps to assess the property, current competition, financing readiness, and the terms that protect your goals.
If you are considering buying, selling, investing, or leasing in Halton, Hamilton, Niagara, or the GTA, the Ana Bastas Real Estate Team is here to help with Strategic Real Estate Advice and a personalized offer strategy. Experience the AB Advantage™.
Ana Bastas, ABR, SRS, SRES, RENE Team Leader | Wealth Builder Ana Bastas Real Estate Team (289) 670-5888
#OntarioRealEstate #OntarioBuyerDeposit #HomeBuyingOntario #HaltonRealEstate #HamiltonRealEstate #NiagaraRealEstate #BurlingtonRealEstate #OakvilleRealEstate #MiltonRealEstate #StrategicRealEstateAdvice
Categories
- All Blogs (1227)
- Ana Bastas Real Estate Team (1)
- Ana Bastas Realtor (1)
- Ana bastas Realty (1)
- Brampton (1)
- Burlington (1)
- Buy & Travel™ Program (12)
- Buyer (209)
- Divorce (16)
- Downsizing (3)
- Events (8)
- First Time Home Buyers (138)
- Georgetown (3)
- Georgetown Buyers (8)
- Halton Hills (264)
- Hamilton (23)
- Holidays (1)
- How To (125)
- Interest Rates (1)
- Investor (5)
- Landlord (91)
- Lifestyle (128)
- Milton (56)
- Mississauga (1)
- Niagara (34)
- Oakville (2)
- Real Estate News (161)
- Realtor (20)
- Renter (94)
- Seller (185)
- Tax's (19)
- Tips (11)
- Toronto (135)
- Wealth Building (5)
- Wellington (2)
- YYZ (107)
Recent Posts

"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "