Buying a Fixer-Upper in Ontario: Do the Renovation Numbers Make Sense?
Buying a Fixer-Upper in Ontario: How to Know If the Numbers Make Sense
“This House Is $200,000 Cheaper. We Can Just Renovate It.”
Maybe.
But the word I pay attention to is:
“JUST.”
We'll just replace the kitchen.
We'll just open this wall.
We'll just finish the basement.
We'll just redo the bathrooms.
We'll just replace the flooring.
We'll just rewire it.
We'll just waterproof it.
We'll just move in while renovating.
And suddenly:
A house that looked like a bargain
isn't necessarily a bargain anymore.
PURCHASE PRICE IS ONLY THE FIRST NUMBER.
What Is a Fixer-Upper?
There isn't one universal definition.
A fixer-upper might need:
Cosmetic updating.
or:
Kitchen + bathrooms.
or:
Major systems.
or:
Structural work.
or:
Extensive renovation.
Those are completely different purchases.
I like to separate fixer-uppers into three broad categories.
Level 1 — Cosmetic Fixer
Potentially:
Paint.
Flooring.
Fixtures.
Lighting.
Cabinet refinishing.
Landscaping.
Cosmetic bathroom updates.
These can still cost money.
But they generally represent a very different project from changing the home's fundamental systems.
Level 2 — Renovation Fixer
Potentially:
New kitchen.
Bathrooms.
Windows.
HVAC.
Significant flooring.
Basement renovation.
Plumbing upgrades.
Electrical upgrades.
Layout modifications.
Now the buyer needs a much more serious:
SCOPE + BUDGET + TIMELINE.
Level 3 — Major Rehabilitation
Potentially:
Structural work.
Foundation.
Major water issues.
Extensive electrical.
Extensive plumbing.
Sewer.
Environmental remediation.
Significant additions.
Major structural reconfiguration.
Multiple building systems approaching replacement.
At this point:
YOU AREN'T JUST BUYING A HOUSE THAT NEEDS DECORATING.
YOU ARE BUYING A PROJECT.
Start With the End Goal
Before asking:
“How much will the renovation cost?”
ask:
“WHAT ARE WE TRYING TO CREATE?”
Is this:
Your long-term family home?
Starter home?
Rental?
Flip?
Multi-generational property?
House you plan to refinance?
Property you're improving gradually?
The same renovation can make sense for one strategy and make no sense for another.
Fixer-Upper Math Starts Before the Offer
I don't want my buyers thinking:
“We'll figure out renovations after closing.”
if the purchase only works financially because they believe renovations will be inexpensive.
If renovation cost materially affects whether the house makes sense:
RENOVATION DUE DILIGENCE IS PART OF PURCHASE DUE DILIGENCE.
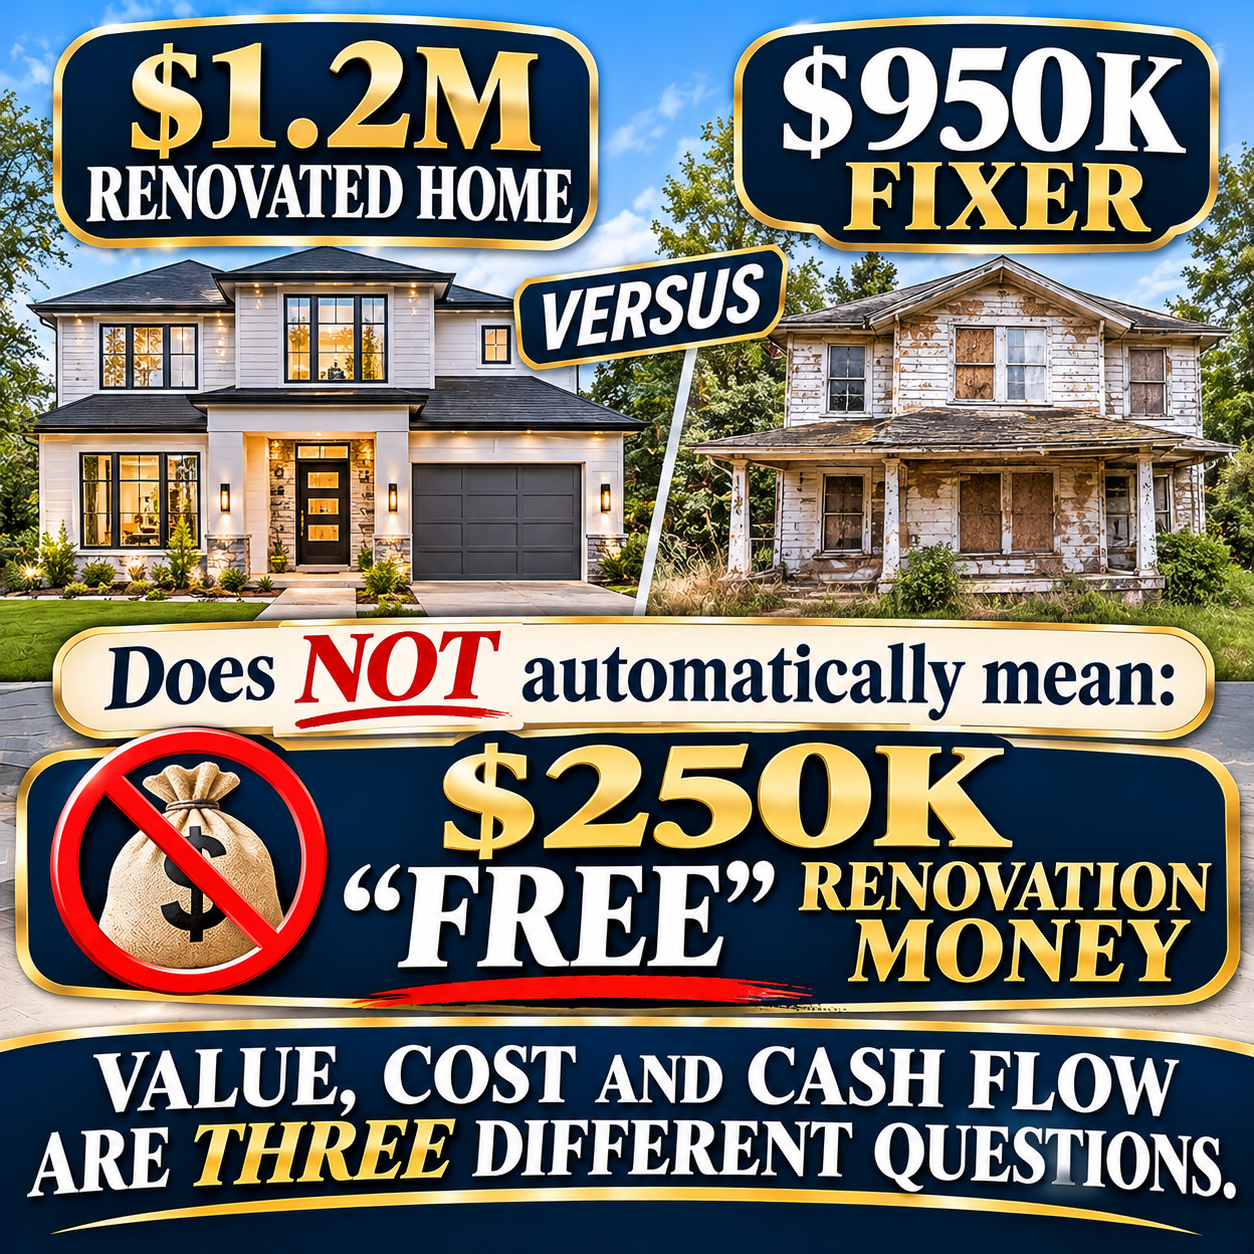
The Wrong Formula
Many buyers calculate:
Move-in-ready comparable = $1,200,000
Fixer = $950,000
Therefore:
“WE HAVE $250,000 TO RENOVATE.”
Not necessarily.
Because the renovated property may not actually be worth $1.2M.
And your renovation could involve:
$150,000 construction
plus:
Professional fees.
Permits.
Financing.
Temporary accommodation.
Storage.
Contingency.
Landscaping.
Furnishings.
Taxes.
Other costs.
THE PRICE DIFFERENCE ISN'T AUTOMATICALLY YOUR RENOVATION BUDGET.
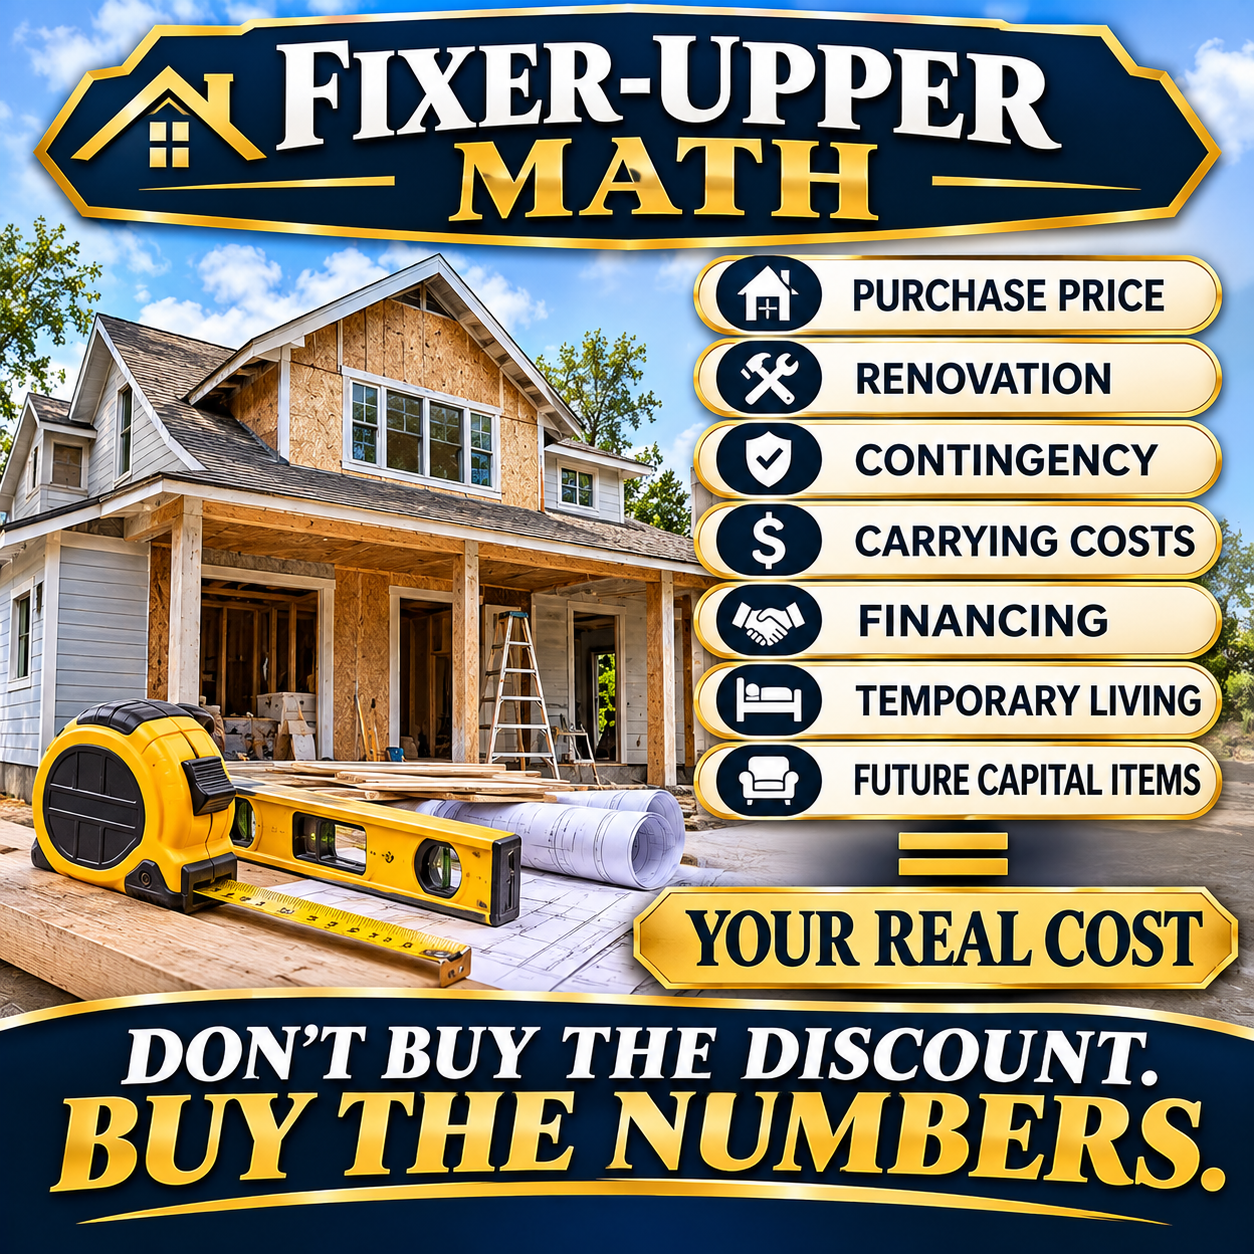
Calculate the Real Project Cost
A more useful framework is:
ACQUISITION
RENOVATION
CONTINGENCY
FINANCING
CARRYING
TRANSACTION COSTS
TEMPORARY LIVING / STORAGE
IMMEDIATE CAPITAL ITEMS
=
TOTAL PROJECT EXPOSURE
Then compare that against:
Your financial capacity.
Your intended use.
Comparable properties.
Expected finished value where relevant.
How long you intend to own it.
Acquisition Costs Matter
Your purchase price isn't necessarily the amount of cash required to acquire the property.
Depending on the transaction, buyers may also have:
Land transfer tax.
Legal fees.
Inspection costs.
Appraisal.
Financing costs.
Insurance.
Adjustments.
Moving expenses.
Potential first-time buyer rebates or other programs are buyer-specific and should be verified rather than assumed.
DON'T SPEND EVERY AVAILABLE DOLLAR ON THE DOWN PAYMENT AND THEN DISCOVER YOU HAVE NO RENOVATION LIQUIDITY.
Renovation Budget
Your renovation budget should start with:
SCOPE.
Not:
Pinterest.
Not:
HGTV.
Not:
“My friend's contractor said kitchens are about $30,000.”
The specific house matters.
Ask:
What are we changing?
What are we keeping?
What needs repair?
What needs replacement?
Are walls moving?
Plumbing moving?
Electrical moving?
Structural changes?
New windows?
New HVAC?
Basement?
Exterior?
Environmental work?
Permits?
DEFINE THE PROJECT BEFORE PRICING THE PROJECT.
Renovation Contingency
Older-home renovations can reveal concealed conditions once walls, floors and ceilings are opened.
That is why a contingency is important.
But we should not prescribe one universal percentage.
The appropriate contingency depends on:
Age.
Project complexity.
Amount of demolition.
Information available.
Contractor.
Professional recommendations.
Risk tolerance.
The principle is:
IF YOUR BUDGET ONLY WORKS WHEN NOTHING UNEXPECTED HAPPENS, YOUR BUDGET MAY BE TOO TIGHT.
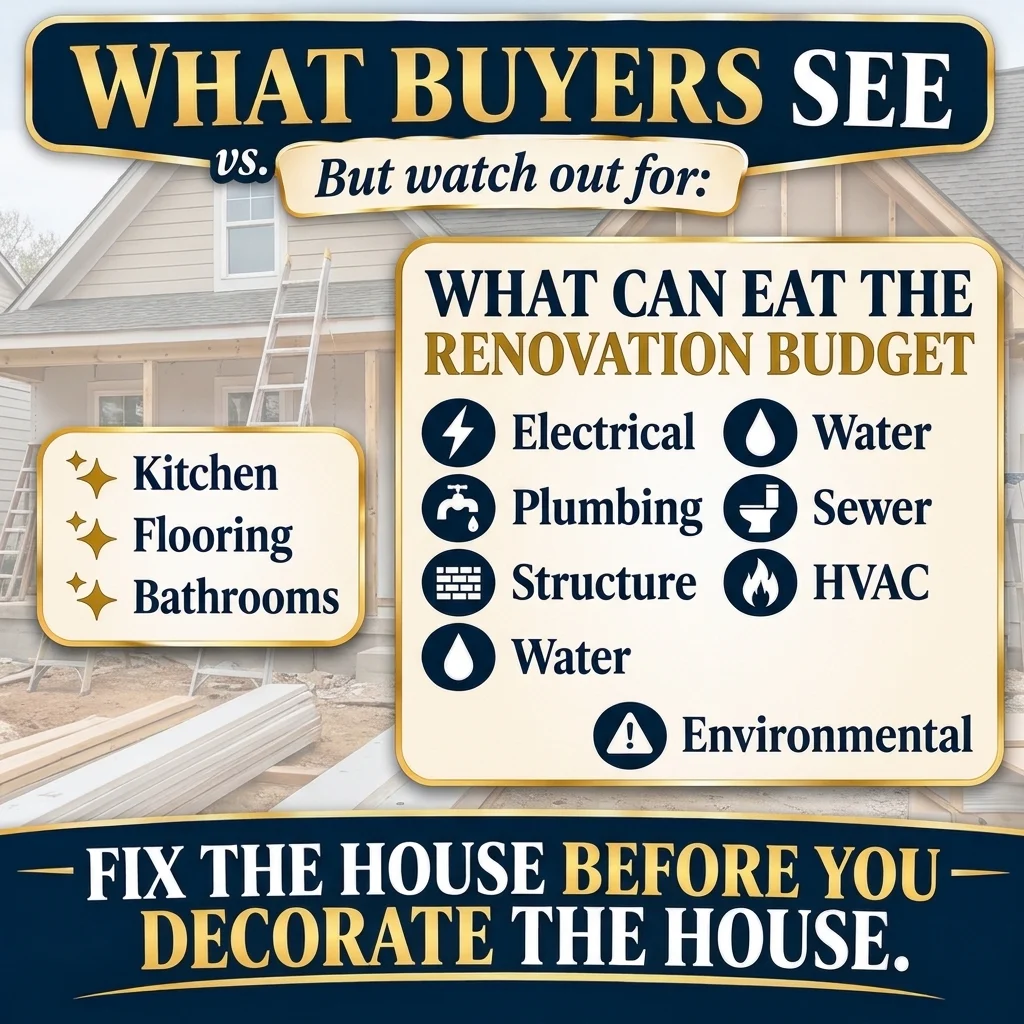
What Can Hide Behind the Walls?
Potential discoveries can include:
Older electrical.
Old plumbing.
Structural modifications.
Water damage.
Environmental materials.
Inadequate previous work.
Insulation issues.
Unexpected framing conditions.
Other concealed components.
That's not proof that every older renovation will uncover a disaster.
It simply means:
DEMOLITION CREATES INFORMATION YOU DIDN'T HAVE BEFORE.
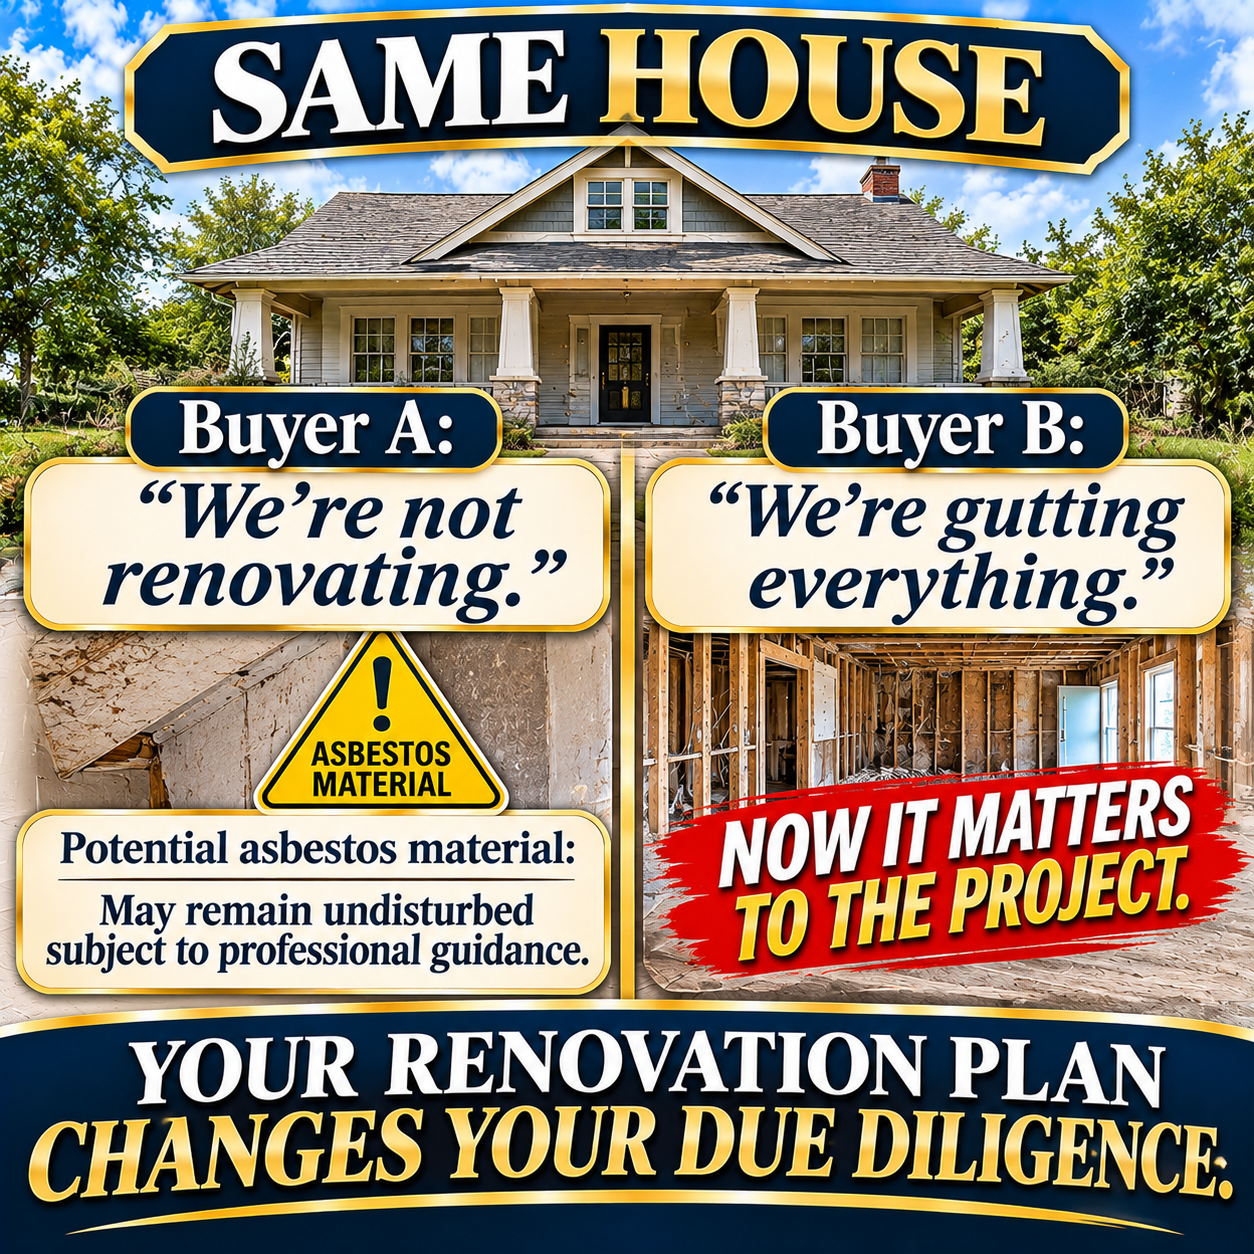
Asbestos Can Change the Renovation Budget
Suppose you plan to:
Remove textured ceilings.
Open walls.
Replace flooring.
Relocate plumbing.
Demolish a bathroom.
If materials that will be disturbed contain asbestos, the project may require:
Appropriate testing.
Professional management.
Additional procedures.
Additional time.
Additional restoration considerations.
THE ASBESTOS MAY NOT HAVE BEEN A PROBLEM UNTIL YOUR RENOVATION PLAN MADE IT RELEVANT.
READ: Asbestos in Older Homes Ontario →
Electrical
If you're already opening walls, electrical upgrades may become part of the renovation discussion.
But first understand:
Existing wiring.
Panel.
Previous upgrades.
Insurance requirements.
Professional recommendations.
Renovation scope.
READ: Knob-and-Tube Wiring Ontario →
READ: Aluminum Wiring Ontario →
Plumbing
A kitchen renovation might reveal:
Older supply lines.
Drainage.
Previous modifications.
Other plumbing conditions.
Moving a sink six feet may be a completely different project from:
Replacing cabinets in the same layout.
LAYOUT CHANGES CAN CHANGE COST DRAMATICALLY.
READ: Old Plumbing in Ontario Homes →
Foundation
A cosmetic renovation budget shouldn't be used to pretend structural work doesn't exist.
If inspection identifies:
Foundation movement.
Structural concerns.
Water conditions.
those issues should be understood before deciding how much money is available for:
Quartz countertops.
READ: Foundation Cracks in Older Homes →
Basement Water
If you're planning a finished basement:
UNDERSTAND THE WATER FIRST.
Don't install:
Flooring.
Framing.
Drywall.
Millwork.
over an unexplained moisture condition.
READ: Water & Basement Moisture in Older Homes →
Sewer
Your renovation budget may include:
$70,000 kitchen.
But if the sewer requires significant work:
That can compete for the same capital.
This is why the invisible systems matter.
READ: Sewer Line Inspections Ontario →
Get Contractor Input Before Firming Up—When It Matters
If your purchase decision depends on whether:
A wall can be removed.
An addition is feasible.
Basement can be finished.
Kitchen can be relocated.
Major renovation fits a particular budget,
consider getting appropriate professional input while you still have the contractual opportunity to investigate, where possible.
The exact professionals may include:
Contractor.
Engineer.
Architect/designer.
Electrician.
Plumber.
Environmental professional.
depending on the project.
Don't Ask a Contractor to Answer Every Question
A contractor is valuable.
But:
Structural engineering question → appropriate structural professional.
Electrical question → qualified electrical professional.
Environmental question → appropriate environmental professional.
Financing question → mortgage professional.
Legal question → lawyer.
Market-value question → Realtor/appraiser as appropriate.
BUILD THE RIGHT TEAM AROUND THE PROBLEM.
Permits
Before buying based on a major renovation vision:
Determine what may require municipal approvals.
Rules depend on:
Municipality.
Scope.
Property.
Structural work.
Plumbing.
Additions.
Change of use.
Other factors.
Don't assume:
“It's inside my house, so I can do whatever I want.”
Verify the specific project.
Zoning
This becomes even more important if the buyer's plan involves:
Addition.
Secondary suite.
Additional dwelling unit.
Parking changes.
Major exterior alteration.
Lot redevelopment.
Rental strategy.
The fact that:
“The neighbour did it”
doesn't prove:
You can.
VERIFY THE PROPERTY—not the street rumour.
Heritage Considerations
If you're buying a character property or century home:
Verify whether heritage considerations apply.
An old house isn't automatically heritage-designated.
But where heritage protections do apply, they may affect renovation options.
READ: Buying a Century Home in Ontario →
Financing the Fixer-Upper
This is where buyers need to involve their mortgage professional early.
Possible financing strategies depend on:
Borrower.
Property.
Purchase structure.
Lender.
Renovation scope.
Available equity/cash.
Do not assume:
“The bank will lend me the renovation money.”
before confirming it.
Don't Spend Your Entire Cash Reserve
A fixer-upper with:
Zero financial cushion
can become stressful very quickly.
Because houses don't care that:
You already spent your budget.
The furnace can still fail.
The sewer can still require work.
The roof can still leak.
Your personal financial situation can still change.
RENOVATION MONEY AND EMERGENCY MONEY SHOULD NOT AUTOMATICALLY BE TREATED AS THE SAME POOL.
A financial professional can help determine an appropriate reserve.
Carrying Costs
If the renovation takes:
Three months.
Six months.
Twelve months.
you may still be paying:
Mortgage.
Property tax.
Insurance.
Utilities.
Condo/road/common fees where applicable.
Financing costs.
Maintenance.
And potentially:
Rent somewhere else.
TIME HAS A COST.
RENOVATION DELAY = MONEY
Every additional month may mean:
🏠 Mortgage carrying
💡 Utilities
🏢 Temporary housing
🛡 Insurance
💰 Financing costs
BUDGET THE TIMELINE—not just the materials.
Temporary Accommodation
Can you live in the house during renovation?
Maybe.
But if there is:
Major demolition.
No kitchen.
Significant dust.
Environmental remediation.
Electrical shutdown.
Plumbing shutdown.
Children.
Pets.
living through construction may not be practical.
Budget:
Rent.
Hotel.
Storage.
Additional moving.
if needed.
Renovation Timeline
The contractor saying:
“About eight weeks”
doesn't mean you should build your entire financial plan around exactly 56 days.
Projects can be affected by:
Permits.
Product availability.
Trade scheduling.
Change orders.
Concealed conditions.
Weather.
Inspection requirements.
Scope changes.
Build flexibility into the plan.
Change Orders
This is where renovation budgets can creep.
Buyer begins with:
Kitchen.
Then:
“While we're here…”
New floors.
New lighting.
New staircase.
New powder room.
New trim.
New doors.
SCOPE CREEP CAN BE JUST AS EXPENSIVE AS HIDDEN CONDITIONS.
Don't Over-Renovate for the Neighbourhood
If resale value matters, understand:
What buyers pay for renovated homes in the area.
A $400,000 renovation doesn't automatically create:
$400,000 of additional market value.
RENOVATION COST ≠ VALUE CREATED.
This distinction is critical.
Renovation Value Is Market-Specific
The same kitchen renovation may affect value differently in:
Georgetown.
Oakville.
Burlington.
Hamilton.
Niagara.
Toronto.
Ottawa.
and differently depending on:
Property type.
Neighbourhood.
Price point.
Buyer expectations.
This is where Ana's real-estate analysis belongs.
Comparable Sales Matter
Before deciding:
“This fixer is a deal,”
compare:
Similar unrenovated properties.
Renovated properties.
Lot.
Size.
Location.
Parking.
Basement.
Functional differences.
Finished quality.
The question isn't:
“What does the nicest renovated house nearby cost?”
It's:
“WHAT WOULD THIS PROPERTY REALISTICALLY COMPETE WITH AFTER THE WORK?”
Don't Underestimate Quality
Two renovations can both be described as:
“Fully renovated.”
One:
Builder/basic finishes.
Another:
High-end millwork, stone, appliances, lighting and custom design.
Finished value depends partly on:
Quality.
Cohesion.
Buyer expectations.
Market segment.
Fixer-Upper for a Flip
If the goal is resale rather than personal use, the analysis needs to become even more disciplined.
Potential considerations include:
Purchase cost.
Renovation.
Financing.
Carrying costs.
Selling costs.
Taxes.
Market risk.
Contingency.
Timeline.
Expected resale.
And tax treatment should be discussed with an appropriate accountant/tax professional.
PROFIT ISN'T SALE PRICE MINUS PURCHASE PRICE.
Fixer-Upper as a Rental
Likewise, an investor should consider:
Total capital invested.
Expected rent.
Operating expenses.
Financing.
Vacancy.
Maintenance.
Capital expenditures.
Property management.
Cash flow.
Future value.
Tax considerations.
A beautiful renovation doesn't automatically make:
A good rental investment.
Fixer-Upper as Your Long-Term Home
The calculation changes.
You may intentionally spend more than the immediate resale value because:
You love the neighbourhood.
You plan to stay 20 years.
You're creating a highly customized home.
That's not necessarily a bad decision.
But understand:
LIFESTYLE VALUE AND MARKET VALUE ARE NOT ALWAYS THE SAME THING.
Should You Buy the Fixer or the Renovated House?
Compare both.
OPTION A — RENOVATED
Higher purchase price.
Less immediate construction.
Potentially easier move.
Less customization.
OPTION B — FIXER
Lower acquisition price.
Renovation capital required.
Greater project risk.
More customization.
Potential value creation.
Potential disruption.
Then compare:
TOTAL COST—not just list price.
Ana's Fixer-Upper Formula
When I'm helping a buyer evaluate a fixer:
1. BUY
What can we realistically acquire it for?
↓
2. INSPECT
What does the house actually need?
↓
3. VISION
What does the buyer want to change?
↓
4. SCOPE
Necessary work vs. desired work.
↓
5. PROFESSIONALS
Contractor + specialists where required.
↓
6. RENOVATION
Property-specific budget.
↓
7. CONTINGENCY
Allowance for uncertainty.
↓
8. CARRY
What does time cost?
↓
9. FINANCING
Where does renovation capital come from?
↓
10. FINISHED VALUE
What does the market support?
↓
11. OWNERSHIP PLAN
Live? Rent? Sell? Hold?
↓
12. RISK
What happens if cost or timeline increases?
↓
13. DECISION
DON'T ASK WHETHER YOU CAN AFFORD TO BUY THE FIXER.
ASK WHETHER YOU CAN AFFORD TO COMPLETE THE PLAN.
Fixer-Upper Buyer Worksheet
Fona, add this to the Ontario Older Home Buyer Due Diligence Toolkit.
ACQUISITION
☐ Purchase price
☐ Land transfer tax
☐ Legal
☐ Inspection
☐ Financing/appraisal costs where applicable
☐ Moving
☐ Immediate insurance
ESSENTIAL REPAIRS
☐ Roof
☐ Foundation
☐ Water
☐ Electrical
☐ Plumbing
☐ Sewer
☐ HVAC
☐ Windows/exterior
☐ Environmental issues
DESIRED RENOVATIONS
☐ Kitchen
☐ Bathrooms
☐ Flooring
☐ Basement
☐ Layout
☐ Lighting
☐ Exterior
☐ Landscaping
PROJECT COSTS
☐ Contractor
☐ Design/architectural
☐ Engineering
☐ Permits
☐ Environmental
☐ Demolition
☐ Construction
☐ Restoration
☐ Contingency
CARRYING
☐ Mortgage
☐ Property taxes
☐ Insurance
☐ Utilities
☐ Temporary accommodation
☐ Storage
☐ Financing costs
☐ Timeline allowance
VALUE
☐ Current market value considered
☐ Renovated comparables reviewed
☐ Finished value estimated conservatively
☐ Over-improvement considered
☐ Intended holding period considered
FINAL
☐ Cash reserve remains
☐ Financing confirmed
☐ Insurance confirmed
☐ Renovation team identified
☐ Risk tolerance considered
☐ Buyer understands total exposure
☐ Numbers still make sense
Frequently Asked Questions
Is buying a fixer-upper worth it in Ontario?
It can be. The answer depends on the acquisition price, required repairs, renovation costs, financing, carrying costs, finished value and your ownership goals.
Is a fixer-upper always cheaper than buying renovated?
No. A lower purchase price can be offset by renovation, financing, carrying and temporary-living costs.
How much should I budget to renovate a fixer-upper?
There is no reliable universal amount. Build a property-specific scope and obtain professional quotations based on the actual house and intended renovation.
How much contingency should I have?
There isn't one percentage appropriate for every renovation. Project complexity, property age, demolition and uncertainty should influence the contingency.
Should I get contractor quotes before buying?
If the purchase decision depends heavily on renovation feasibility or cost, professional input before becoming firm can be valuable where the agreement and access allow.
Can I finance renovations with my mortgage?
Some financing options may allow renovation-related funding, but eligibility and structure vary. Discuss the specific property and project with a qualified mortgage professional before relying on renovation financing.
Does a $100,000 renovation add $100,000 to home value?
Not necessarily. Renovation cost and market value created are different things.
Should I buy a fixer-upper with asbestos?
The presence of asbestos-containing material does not automatically make the property unsuitable. Its condition and whether your renovation will disturb it are important considerations requiring appropriate professional advice.
Should I buy a fixer-upper with foundation problems?
First determine what the actual condition is, what work is recommended and what it costs. “Foundation problem” is too broad to make a purchase decision from.
Can I live in a house while renovating it?
Sometimes, but it depends on the scope, utilities, environmental considerations, safety and your household. Include alternative accommodation in your planning where necessary.
Is a fixer-upper good for a first-time buyer?
It can be, but first-time buyers should realistically assess available cash, financing, project-management capacity, renovation risk and emergency reserves.
What should I fix first in an older home?
Generally, understand and prioritize significant building, safety and water-related conditions before purely cosmetic improvements, based on professional recommendations for the specific property.
Categories
- All Blogs (1413)
- Ana Bastas Real Estate Team (1)
- Ana Bastas Realtor (1)
- Ana bastas Realty (1)
- Brampton (2)
- Burlington (10)
- Buy & Travel™ Program (12)
- Buyer (348)
- Community News (2)
- Divorce (22)
- Downsizing (21)
- Events (73)
- First Time Home Buyers (154)
- Georgetown (38)
- Georgetown Buyers (8)
- Halton Hills (272)
- Hamilton (29)
- Holidays (18)
- How To (140)
- Interest Rates (11)
- Investor (51)
- Join ABR Team (4)
- Landlord (105)
- Lifestyle (177)
- Milton (83)
- Mississauga (3)
- Mortgage (23)
- Niagara (39)
- Oakville (6)
- Older Home (6)
- Real Estate News (235)
- Realtor (73)
- Renter (99)
- Seller (266)
- seller education series (3)
- Tax's (28)
- Tips (42)
- Toronto (148)
- Wealth Building (15)
- Wellington (4)
- YYZ (105)
Recent Posts
"My job is to find and attract mastery-based agents to the office, protect the culture, and make sure everyone is happy! "